
Interest rates jumping over the last several weeks has an industry reacting to meet a fear-based decision making process in home buying. New Builders are dumping advertising dollars into mortgage rate incentives and the process of finding your dream home has quickly transformed into finding your dream interest rate. But why would you make a long-term decision that impacts the quality of life for your and your family solely on a short term situation – that you have the power to change?
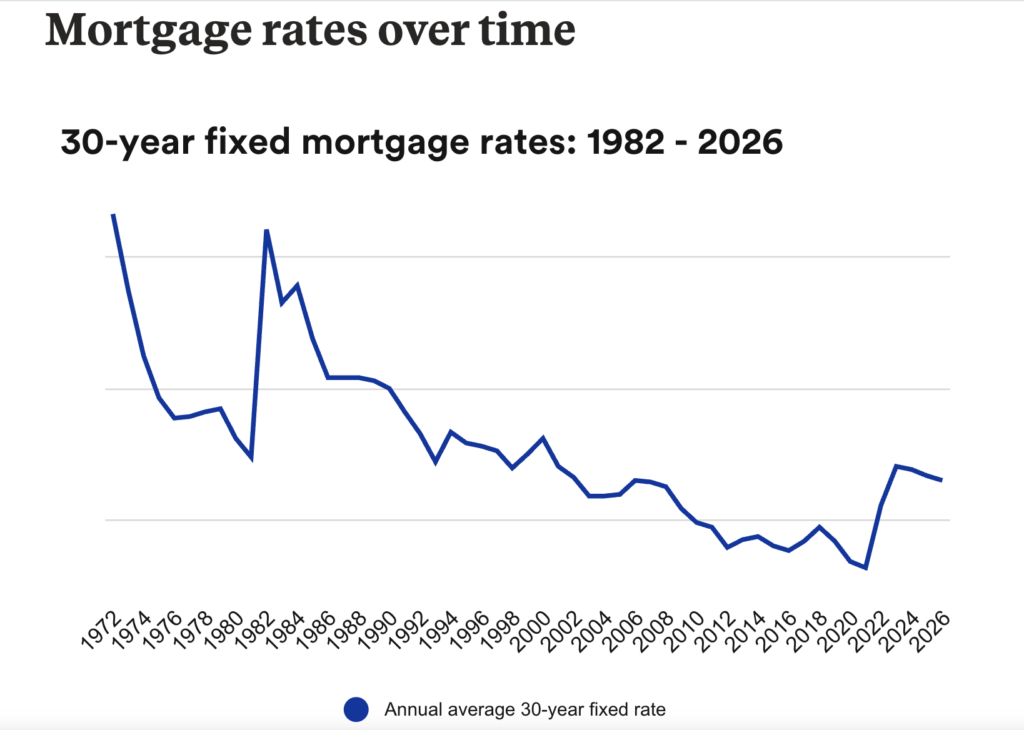
Over the last 30 years interest rates in home buying have been on a decrease in what we call “the norm” and yet world events, economical changes and even elections have illustrated impact to the eb and flow of these trends. Interest rates change daily. Just in the last week we’ve seen differentials of .3 points at market opening. And during a time of war when uncertainty looms with elections coming up, there’s no real prediction of what may happen. But what we do know for sure is that interest rates will continue to change – historically speaking…..
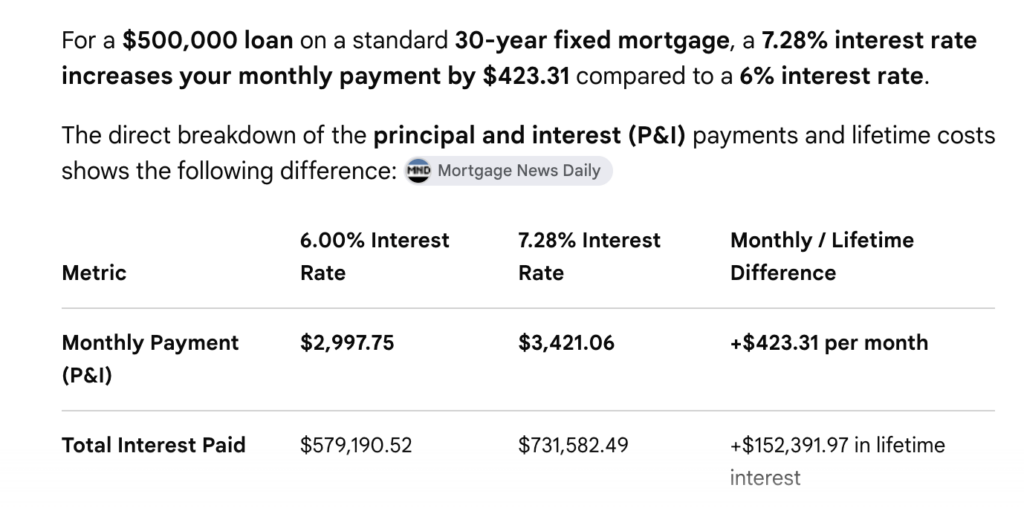
If you were take the 3 year low and compare it to the recent high (7.28%) on a purchase price of $500,000 for a new home you would roughly be looking at about $300 per month more on your mortgage. This might be significant when you’re thinking about the long term expenses adding up that could go towards other things like your car insurance or your gas to and from work. However, the major thing to consider is that this rate isn’t a forever commitment.
If you look at interest rate fluctuations just in the last year we see a 1.28 differential – that’s a $423 per month difference in monthly payment on a $500,000 loan. So you might say timing is VERY IMPORTANT to making a purchase on a new home when these rates are low – but again…. you aren’t married to the rate.
REFINANCE 6 SHORT MONTHS AFTER PURCHASE
Did you know that you can refinance your home in as little as 6 months from your date of purchase? Likewise, did you know that most mortgage lenders allow you to refinance anytime within the first 3 years following your purchase at no cost? This means that the FEAR of buying a home during a time of high interest rates should not be the basis of deciding to settle for a home less than your favorite or buying into the smoke and mirror ad campaigns that cause you to look first at price and second at home quality and enjoyability for the long term living situation that impacts your quality of life.
But what if rates go up even further?
Again, rates change everyday. The up and down motion is historically a mainstay that prompts overall predictability. But where there is question there are always predictions from the folks who live and breathe mortgage interest rates and have lived inside of this daily roller coaster ride for decades and beyond. So what are the experts saying?
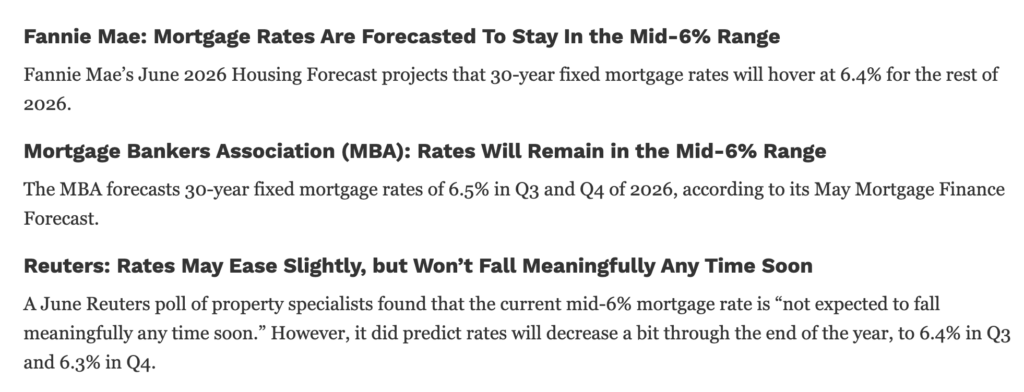
All expert sources cited this week in Forbes magazine predict the mortgage interest rates to find their way down to the 6.3% and 6.5% range rather quickly, (over the next 6 months). That prediction would mean that if you bought a $500,000 home today, you can refinance in six months and cut your monthly mortgage payment by over $200 a month. Here is the article if you’d like to read through it yourself: https://www.forbes.com/advisor/mortgages/mortgage-interest-rates-forecast/
But in the bigger picture of things, there’s even another option that you might should consider; temporary buy-downs. When you buy-down an interest rate upfront with cash to decrease rate points, the money is buying you a 30-year fixed rate. But, are you planning to live in that home for 30 years? Jobs change, family lifestyle stages chance and there’s a good chance that your situation will one day outgrow your home ownership needs that you have today. Rather than placing real money into interest rate savings over a 30 year period, consider short term rate buy-down options as you await for the perfect opportunity to lock-in a refinance on a lower rate.
For example, you can do a 3/2/1 buy-down on your rate that gets you as low as 5% on your first year of payments, then goes up to 6% after a year and levels out in year 3. Do you think you might have a chance to take advantage of the fluctuations in your favor and refinance before you hit the 3 year mark? You can even do a shorter-term buy down for only 2 years and if the experts are right in their predictions, you can refinance at a lower rate and get a refund on the cash you placed into that buy-down. Doesn’t that sound better (and wiser) than settling for a home you don’t love and/or using your cash or builder incentives to eat away at a 30-year projection on your ever-changing livelihood?
The real answer to all of this is to weigh your options and work with experts who can break down those options for you and make it possible to meet your short term monthly payment goals AND buy the home you absolutely love and will be happy with for years to come and many memories in the making with you and your family and friends.
I’m not a mortgage lender but I do know some of the best in the business who I’ve had the pleasure to work with and see them in action over the last 13 years. I’ve bought and sold many homes for my clients, friends and family members (and for myself to) and I’m happy to connect you with the ones I call “the good guys” in the mortgage and lending business.
I hope this writing was helpful and I hope you get married to the home you absolutely love (while dating the rates to make wise decisions) and that one day you remember the 10 minutes of your time that you spent reading my words. I truly do hope to help others and leave a positive impact in some way.